How SAFEs and Convertible Notes Affect Startup Valuation, Dilution & Cap Tables
 Jeet Chaudhary
on
Introduction
Founders raising a pre-seed or seed round almost always reach for a SAFE or a convertible note, and for good reason. Both instruments let a company take in cash in days instead of weeks, without the cost and negotiation of a fully priced equity round. That speed comes with a tradeoff most founders do not see coming: every SAFE and every convertible note is a claim on tomorrow's cap table, and the real cost of that claim usually is not visible until the next priced round closes and the conversion math finally runs.
For founders, CFOs, and finance leaders, this creates a planning blind spot. A stack of SAFEs at different valuation caps can quietly commit away a large share of the company before a single share of preferred stock is ever issued. A convertible note's accrued interest, maturity date, and debt status carry consequences that a SAFE does not. And conversion itself is a valuation and tax event, not just a paperwork exercise, with 409A and Qualified Small Business Stock implications that catch even experienced founders off guard.
This guide walks through how SAFEs and convertible notes actually convert, how valuation caps and discount rates drive dilution, why cap tables understate real ownership until conversion, and what the 2026 tax and securities law landscape means for founders and investors structuring these rounds today.
Key Takeaways
- SAFEs and convertible notes defer valuation negotiation to a future priced round, letting startups raise capital faster than a traditional equity round allows.
- Convertible notes accrue interest and carry a maturity date, while standard SAFEs carry neither, which changes the pressure each instrument places on the company over time.
- Post-money SAFEs fix each investor's ownership percentage at issuance, which is simpler for investors but means every new SAFE comes directly out of the founders' remaining ownership.
- A valuation cap is a ceiling on conversion price, not a company valuation, and should never be used as a substitute for a real business or 409A valuation.
- Discount rates and caps both work by lowering the investor's effective conversion price, and instruments with both typically convert at whichever price is more favorable to the investor.
- A fully diluted cap table, one that models every outstanding SAFE and note at its likely conversion terms, is the only accurate way to see real ownership before a priced round closes.
- Conversion is generally a material event that calls for a fresh 409A valuation, and the QSBS holding period start date for SAFEs remains an unsettled question that deserves specific tax advice.
What Are SAFEs and Convertible Notes, and Why Startups Use Them
Both instruments exist to solve the same problem: an early-stage company and its investors often cannot agree on a fair valuation before the company has meaningful revenue, users, or a finished product. Rather than negotiate a price nobody can defend, the company and investor agree to defer that pricing decision to a future, better-informed moment, typically the company's next priced equity round.
Convertible Notes: Debt With an Equity Upside
A convertible note is a short-term debt instrument. The company borrows money from the investor and agrees to a principal amount, a stated interest rate (commonly in the 4% to 8% range), and a maturity date, generally 12 to 24 months out. If the company raises a qualifying priced round before maturity, the note typically converts into equity rather than being repaid in cash. If no such round happens by maturity, the note becomes due and payable, or, more commonly in practice, the company and investor negotiate an extension, a conversion at a pre-agreed maturity valuation, or repayment.
Two mechanics are easy to underweight. First, because the note accrues interest, the balance that actually converts is principal plus accrued interest, not just the original check amount, so noteholders convert into more shares than a simple percentage of the investment would suggest. Second, because a note is debt, an unpaid note sits on the company's balance sheet as a liability and, in a wind-down or sale, is generally repaid ahead of both preferred and common equity, consistent with its debt priority.
SAFEs: Equity-Like Instruments Without the Debt
A SAFE (Simple Agreement for Future Equity) was introduced by the startup accelerator Y Combinator in 2013 as a simpler alternative to the convertible note. A standard SAFE carries no interest rate, no maturity date, and no repayment obligation. It converts automatically into equity at the company's next qualified financing, or is treated according to its terms in a liquidity event or dissolution. Because there is no debt and no maturity date forcing a decision, a SAFE removes the deadline pressure a note creates, but that same feature means the timing of conversion depends entirely on when, or whether, the company later raises a priced round.
It is worth stating plainly: a SAFE is still a security under federal law. The U.S. Securities and Exchange Commission's Office of Investor Education and Advocacy has specifically cautioned investors that SAFEs, despite the name, are not risk-free and must be offered and sold under an available registration exemption, the same as any other security.
Post-Money vs Pre-Money SAFEs: The Dilution Math Founders Get Wrong
Early SAFEs were priced on a pre-money basis, meaning the valuation cap referred to the company's value before the new investment. That structure created a well-documented problem: when a company issued several pre-money SAFEs at different caps, the SAFEs diluted each other unpredictably as they converted, and founders often could not calculate their real ownership until every SAFE and the priced round converted at once. In 2018, Y Combinator introduced the post-money SAFE specifically to fix this ambiguity, and it is now the dominant SAFE format used by U.S. startups.
Under a post-money SAFE, the valuation cap fixes the investor's ownership percentage of the company as it exists immediately after all outstanding SAFEs convert, before the new round's shares are issued. The formula is straightforward:
SAFE Ownership Percentage = Purchase Amount ÷ Post-Money Valuation Cap
This is genuinely simpler for the investor, who knows their exact percentage the moment they sign. The tradeoff lands on the founders. Because each post-money SAFE's percentage is fixed and additive, every new SAFE a company issues comes directly out of the founders' remaining ownership, not out of the other SAFE holders' stakes. A company that issues several SAFEs over 12 to 18 months, each seemingly reasonable in isolation, can find that 25% or more of the company has already been committed away, and because none of that shows up as issued shares until conversion, a standard cap table snapshot will not reveal it. This is generally referred to as SAFE stacking, and it is one of the most common sources of founder surprise at Series A.
How Valuation Caps and Discount Rates Actually Work
Valuation cap. The cap is a ceiling, not a valuation of the company. It sets the maximum effective price at which the SAFE or note converts, protecting the early investor from paying the same price as new investors if the company's value has risen sharply since the SAFE was signed. If the company's next round prices well below the cap, the cap has no effect and the instrument converts on the round's actual terms (subject to any discount).
Discount rate. Many SAFEs and notes also carry a discount rate, typically between 10% and 25%, with 20% the most common figure in current market practice. The discount gives the early investor a lower price per share than the new round investors are paying, rewarding the early investor for taking risk before the company's value was proven. When an instrument has both a cap and a discount, it almost always converts at whichever produces the lower price per share, and therefore more shares, for the investor.
A simplified illustration: suppose a company's next priced round sets a $2.00 price per share for new investors. A convertible note with a 20% discount and no cap converts at $1.60 per share ($2.00 x 80%). If that same note also carried a valuation cap that implied a $1.40 per share conversion price, the noteholder would convert at $1.40, the lower of the two, because the cap is more favorable in that scenario.
Most Favored Nation (MFN) clauses. Instead of, or alongside, a cap and discount, some very early SAFEs and notes include an MFN provision, giving the investor the right to elect the terms of a later, more favorable SAFE or note the company issues to someone else before the priced round. MFN clauses are common in pre-traction rounds where neither party wants to commit to a cap yet, but they require careful tracking, since exercising an MFN right changes that investor's conversion terms after the fact.
The Cap Table Problem: Why SAFE and Note Stacks Create an Invisible Dilution Overhang
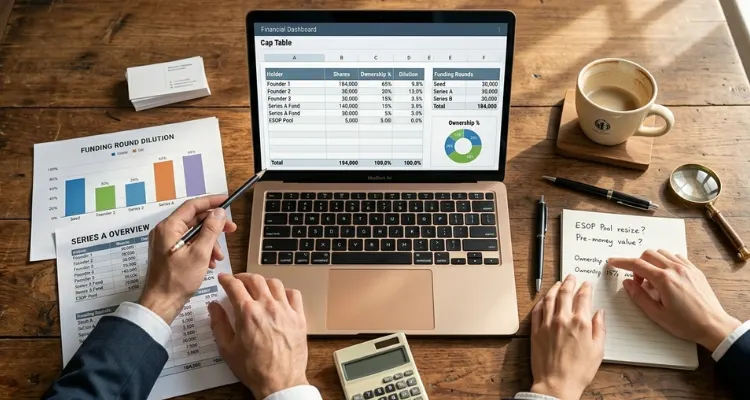
A cap table that lists only currently issued shares understates the real ownership picture for any company with SAFEs or notes outstanding. The accurate view is the fully diluted cap table: issued shares, the option pool, and every outstanding SAFE and note modeled at its likely conversion terms. Skipping this step is the single most common reason founders are unpleasantly surprised by their ownership percentage after a priced round closes.
Modeling a Priced Round with an Existing SAFE and Note Stack
Consider a simplified example. A company with founders holding 100% of the equity raises two post-money SAFEs:
- SAFE 1: $250,000 invested at a $5,000,000 post-money valuation cap, no discount. Ownership = $250,000 ÷ $5,000,000 = 5%.
- SAFE 2: $500,000 invested at an $8,000,000 post-money valuation cap, no discount. Ownership = $500,000 ÷ $8,000,000 = 6.25%.
Before any priced round, the company's fully diluted ownership already looks like this: founders 88.75%, SAFE 1 investor 5%, SAFE 2 investor 6.25%.
The company then closes a Series Seed priced round: $2,000,000 raised at a $10,000,000 pre-money valuation, or $12,000,000 post-money. New investors receive $2,000,000 ÷ $12,000,000, or 16.67% of the company on a post-round basis. Because the SAFEs convert into equity immediately before the new round's shares are issued, everyone else, founders and SAFE holders alike, is diluted by the same proportional factor, roughly 83.33%, while keeping their relative share of that remaining pie. The resulting post-round table looks approximately like this:
| Holder | Pre-round ownership | Post-round ownership |
|---|---|---|
| Founders | 88.75% | 73.96% |
| SAFE 1 investor | 5.00% | 4.17% |
| SAFE 2 investor | 6.25% | 5.21% |
| New Series Seed investors | 0.00% | 16.67% |
Two things drive the outcome. First, the SAFE percentages were fixed at issuance and simply carried forward proportionally, which is why post-money SAFEs are easier to model than the pre-money versions they replaced. Second, and easy to miss, is that many priced rounds also call for expanding the employee option pool before the new investment closes, sized as a percentage of the post-round company. Where that expansion is negotiated, it is customarily absorbed by the pre-round shareholders, meaning founders and existing SAFE and note holders, rather than by the new investors, which can meaningfully deepen the dilution shown above depending on how the round is negotiated. Whether and how much of a pool expansion is included is a matter of negotiation between the company and the new investors in each specific round, not a fixed rule.
Conversion Mechanics at a Priced Round: What Happens on Close
Most SAFEs and convertible notes define a "qualified financing" as a priced equity round that raises at least a stated minimum amount of new money, often $1,000,000 to $2,000,000 or more, in exchange for a new series of preferred stock. When that trigger is met, outstanding SAFEs and notes typically convert into the same class of preferred stock the new investors are receiving, at the price determined by the lower of the cap-implied price and the discounted price, subject to the specific terms of each instrument.
If a company is acquired, or dissolves, before a qualified financing occurs, SAFEs and notes are treated according to the liquidity and dissolution provisions written into each agreement, which vary by instrument and by version. As a general matter, convertible notes, being debt, are typically repaid as unsecured creditors ahead of both preferred and common equity in a sale or wind-down, while SAFEs typically convert to common stock or receive a payout tied to the greater of the purchase amount or an as-converted amount, generally ranking ahead of common stock but behind priced preferred stock. Because these terms differ across SAFE and note versions, founders and investors should read the specific liquidity provisions in the instrument rather than assume a standard outcome.
If a convertible note reaches its maturity date without a qualifying round, the note does not automatically disappear or automatically convert. The company generally has three practical paths: negotiate an extension of the maturity date, agree to convert the note into equity at a pre-negotiated maturity valuation, or repay the principal and accrued interest in cash. Which path applies depends entirely on the note's specific maturity provisions, and running out of runway with an unresolved note at maturity can create real cash flow and negotiating leverage problems for a company.
Common Mistakes Founders Make with SAFEs and Convertible Notes
Several recurring errors show up across early-stage companies, and most are preventable with disciplined cap table hygiene
- Not modeling the fully diluted cap table before signing. Many founders evaluate each new SAFE or note in isolation, without recalculating cumulative dilution across everything already outstanding.
- Treating the valuation cap as the company's actual valuation. A cap is a ceiling used only to price conversion; using it as a marketing figure, an internal valuation benchmark, or a substitute for a proper business valuation can create real confusion with investors, employees, and even auditors later.
- Ignoring accrued interest on notes when estimating dilution. Even a modest stated interest rate compounds over an 18 to 24 month note term and increases the share count issued at conversion.
- Overlooking that a priced round is generally a material event for 409A purposes. A capital structure change of this size generally calls for a fresh independent valuation rather than continued reliance on the prior 409A report.
- Assuming the Qualified Small Business Stock holding period starts on the SAFE purchase date. As discussed below, this question does not have settled IRS guidance, and assuming the earlier date without documentation can be a costly mistake for investors relying on Section 1202.
- Missing federal and state securities filings. Each SAFE and note closing is a securities sale. Companies relying on the Regulation D exemption to sell SAFEs and notes without full SEC registration are generally required to file a Form D with the SEC, along with any required state notice filings, within the applicable deadlines.
409A Valuation, QSBS, and Tax Considerations at Conversion
Why Conversion Usually Triggers a New 409A Valuation
A 409A valuation is an independent appraisal of a private company's common stock fair market value, used to set a defensible strike price for employee stock options under the IRS safe harbor rules for nonqualified deferred compensation. A professional 409A valuation typically allocates the company's total equity value across its full capital structure, preferred stock, SAFEs, notes, options, and common stock, using an option pricing or similar waterfall model. Adding a substantial SAFE or note stack, or converting that stack into a new class of preferred stock at a priced round, materially changes that capital structure and generally changes the implied fair market value of the common stock. Because a new financing round is widely treated as a material event under the safe harbor framework, most companies commission a fresh 409A valuation at or shortly after closing a priced round rather than continue relying on a stale report. Companies with meaningful SAFE or note stacks should have their 409A valuation services provider review the pro forma capitalization before the round closes, not after, since the conversion terms materially affect the resulting valuation.
QSBS: A Genuinely Unsettled Question for SAFE Conversions
Section 1202 of the Internal Revenue Code allows non-corporate holders of Qualified Small Business Stock in an eligible C corporation to potentially exclude a significant portion, and in many cases all, of their capital gain on a future sale, subject to per-issuer and gross-asset limits. Under the One Big Beautiful Bill Act, signed into law on July 4, 2025, the rules for QSBS acquired after that date changed materially: instead of a single five-year holding period required for a 100% exclusion, the law now applies a tiered structure of a 50% exclusion after a three-year hold, 75% after four years, and 100% after five years, and it raised the per-issuer gain exclusion cap from $10 million to $15 million and the qualifying corporation's aggregate gross asset threshold from $50 million to $75 million, both indexed for inflation in tax years beginning after 2026. QSBS acquired on or before July 4, 2025 continues to follow the prior rules, generally a five-year hold for a full exclusion and the original $10 million and $50 million thresholds.
The open question for SAFE investors is when the holding period actually begins. Practitioners are genuinely divided, and the IRS has not issued formal guidance resolving it. One position treats a SAFE as stock, or as a contract right to acquire stock, from the date the SAFE is purchased, which would start the clock early. The competing position treats a SAFE as a prepaid forward contract, meaning the investor does not actually hold stock, and therefore the holding period, for QSBS purposes, only begins on the date the underlying preferred stock is actually issued at conversion. Because a mistaken assumption about the start date can mean the difference between qualifying for the exclusion and not, investors and companies relying on Section 1202 should document conversion dates carefully and get advice specific to the SAFE's exact terms rather than assume the earlier date applies. This uncertainty generally does not apply the same way to convertible notes, since a note is more clearly a debt instrument until it actually converts into stock.
Imputed Interest and the Applicable Federal Rate
Because a convertible note is a debt instrument, its stated interest rate matters for tax purposes, not just for the balance owed at conversion. The IRS publishes Applicable Federal Rates, or AFRs, every month by revenue ruling, and a loan priced below the relevant AFR can trigger imputed interest rules that treat the difference as taxable income to the lender, even though no extra cash changed hands. For example, the short-term AFR for September 2026 is 4.18% on an annual compounding basis, and this figure changes monthly. Most convertible notes sidestep this issue by pricing their stated interest rate at or above the relevant AFR at issuance, which is one reason few founder-drafted, zero-interest convertible notes hold up well under scrutiny.
Practical Recommendations: A Founder's Framework for Structuring SAFEs and Notes
- Build and maintain a live, fully diluted cap table model. Include every outstanding SAFE and note at its current cap, discount, and accrued balance, not just issued shares, and update it every time a new instrument is signed.
- Choose the instrument that fits the round, not just the template you were handed. Post-money SAFEs offer simplicity and speed; convertible notes may fit better when investors want interest and a hard deadline; pre-money SAFEs are increasingly uncommon and generally worth avoiding given the stacking ambiguity they create.
- Set valuation caps that reflect a realistic growth trajectory, rather than the highest number an investor will accept, since an unrealistic cap can create a painful reset, or a structurally low common stock valuation, at the next round.
- Track every SAFE and note in a single ledger listing amount, cap, discount, MFN status, and issue date, and reconcile that ledger against your legal documents at least quarterly.
- Loop in your valuation and tax advisors before you close a priced round, so a refreshed 409A valuation and any QSBS documentation happen on schedule rather than after the fact.
- Confirm your securities filings are current. Track each closing's Form D filing deadline and any state blue-sky notice requirements alongside your cap table, not as an afterthought.
The Role of Virtue Advisors in Startup Financing and Cap Table Strategy
Founders rarely need help understanding that a SAFE or convertible note is a fast way to raise money. What is harder to see without outside expertise is exactly how much ownership, tax exposure, and reporting obligation comes attached to that speed. Virtue Advisors works with founders and finance leaders through each stage of this process, starting with startup and business valuation services that model the fully diluted impact of a SAFE or note stack before a term sheet is signed, not after.
At conversion, that same team can deliver an updated 409A valuation that properly reflects the company's new capital structure, helping the board defend option strike prices under the IRS safe harbor. On the tax side, Virtue Advisors' business tax planning services help founders and investors think through Section 1202 documentation, entity structure, and the timing questions that come with QSBS eligibility, while monthly accounting and bookkeeping services make sure convertible notes are properly tracked as liabilities and SAFEs are recorded consistent with GAAP until conversion, so the company's books do not quietly drift out of sync with its actual cap table. For founders who want an ongoing sounding board on financing strategy, Virtue Advisors' financial advisory services provide the CFO-level perspective many early-stage companies need but are not yet ready to hire in-house.
Conclusion
SAFEs and convertible notes exist to solve a real problem: pricing a company that does not yet have enough data to price fairly. Used with discipline, both instruments let founders raise capital quickly without giving away more than they intend to. Used without a clear model of cumulative dilution, cap stacking, and conversion mechanics, they can quietly reshape a cap table in ways that surprise everyone at the table by the time a priced round finally closes. The difference between the two outcomes usually comes down to whether someone was tracking the fully diluted picture from the first SAFE onward, and whether the company's valuation and tax positions were revisited at each meaningful milestone rather than left on autopilot.
If your company is planning a SAFE or convertible note raise, sitting on a stack that has not been modeled recently, or approaching a priced round that will trigger conversion, a conversation with a valuation and tax team before you sign the next term sheet is generally far less expensive than untangling the dilution and compliance questions afterward.
Frequently Asked Questions
Jeet Chaudhary
Jeet Chaudhary serves as the Chief Operating Officer at Virtue Advisors, where he leads the firm’s Global Control Centre and oversees end-to-end operational excellence.