ESOP Feasibility Study: Is Your Business a Good Candidate for an ESOP?
 Jeet Chaudhary
on
Introduction
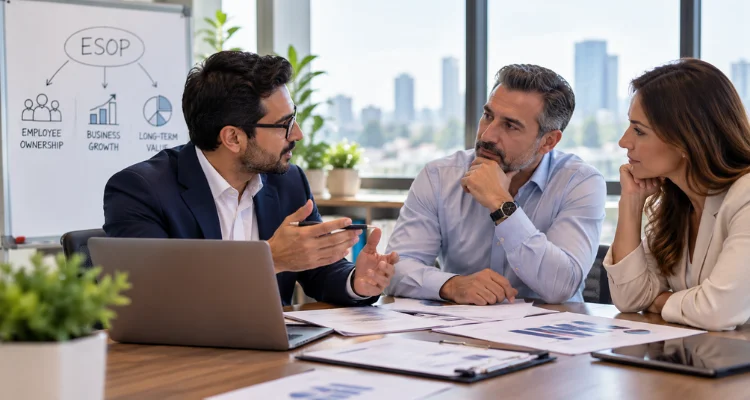
Selling your company to your employees sounds simple until you ask how they will pay for it. The answer comes from company cash flow, a bank loan and often a seller note. An ESOP feasibility study tests whether those pieces fit before you spend on lawyers, trustees and plan documents.
The guide below explains what a study covers, which businesses tend to pass, and the tax and payroll rules that decide many studies. It also covers the repurchase duty that follows every ESOP. It is general information, not tax, legal or investment advice.
Key Takeaways
- An ESOP feasibility study is a go or no-go test run before any binding commitment.
- Published size screens differ, so payroll capacity and cash flow matter more than headcount.
- In a C corporation, deductible contributions to repay ESOP loan principal are capped at 25 percent of participant pay.
- A C corporation seller can defer capital gains under Section 1042 when the ESOP owns 30 percent or more after the sale.
- Every private-company ESOP must plan for buying back shares from departing employees.
What Is an ESOP Feasibility Study?
An ESOP feasibility study is a financial and strategic analysis that tests whether selling a business to an employee stock ownership plan can work for the owner, the company and its lenders. It models a value range, debt capacity, cash flow, taxes and the effect on existing benefit plans before anyone signs a binding agreement.
A study usually answers five questions. What might the ESOP pay? How much debt can the company carry? Which tax structure fits? How will the sale affect the 401(k) and other plans? Can cash flow fund future share buybacks?
Independent advisors prepare the study, often a valuation firm, an ESOP advisory firm or a CPA firm working with ESOP counsel. Our guide to what an ESOP is covers the basic structure first.
Is Your Business a Good Candidate for an ESOP?
A business is a good ESOP candidate when it has steady profits, a stable workforce, a management team that can run the company after the owner steps back, and an owner who values legacy as much as top price. Size matters, but published screens differ, so treat headcount as a first filter rather than a verdict.
The two leading screens, as published in 2026, disagree. The NCEO pre-feasibility toolkit suggests at least 15 to 20 employees and the ability to absorb setup costs of generally at least $125,000.
Project Equity advises 40 or more employees and lists $750,000 of EBITDA as a profitability marker. One likely reason for the gap is fixed cost: setup and annual costs weigh more on a small company, so smaller firms need stronger margins.
Other signs point toward a good fit:
- Profits have held up through several business cycles.
- Managers below the owner already make key decisions.
- The owner can wait for part of the price through a seller note.
- The company is not dependent on one customer or one person's relationships.
A business that fails these screens still has options. Owners can look at a partial sale, a management buyout or other forms of employee ownership, often as part of broader succession planning.
Can Your Payroll Support ESOP Debt?
Payroll matters because federal tax law limits how much ESOP loan principal a company can deduct each year, based on what it pays plan participants. A company whose payroll is small relative to the price may not deduct principal payments fast enough, which stretches the loan or shrinks the deal.
Section 404(a)(9)(C) carves S corporations out of the ESOP rule, so they fall under the general stock bonus limit in Section 404(a)(3) with no separate interest treatment. For a C corporation, Section 404(a)(9) of the Internal Revenue Code caps deductible contributions for loan principal at 25 percent of participant compensation, and treats interest separately.
| Test Step | Sample Company |
|---|---|
| Annual payroll of ESOP participants | $2,000,000 |
| Deductible principal limit at 25 percent | $500,000 per year |
| Bank loan to fund the purchase | $3,000,000 |
| Annual principal on a seven-year schedule | About $428,600 |
| Result | Fits under the limit, with modest room for growth |
The sample uses illustrative figures for a C corporation and a seven-year loan to show how a study tests the limit.
Studies also test per-person compensation caps and, for an S corporation, the tighter general limit. A result that sits close to the cap is a warning sign, because payroll can fall in a downturn while the loan payment does not.
How Do C and S Corporation Rules Change the Study?
C and S corporations offer different tax benefits in an ESOP sale. A C corporation seller may defer capital gains through a Section 1042 rollover, while an S corporation owned by an ESOP may pay little federal income tax on the ESOP's share of profits. A feasibility study compares both paths before the deal is set.
The SECURE 2.0 Act of 2022 adds Section 1042(h) for sales after December 31, 2027, letting S corporation sellers elect deferral on up to 10 percent of the amount realized. Under Section 1042, the full deferral needs a domestic C corporation, an ESOP owning at least 30 percent after the sale, and shares held for 3 years.
| Structure | Seller Deferral | Tax on the ESOP's Share | Key Condition |
|---|---|---|---|
| C corporation | Full Section 1042 deferral available | Corporate tax applies | Reinvest from 3 months before to 12 months after the sale |
| S corporation, sales through 2027 | No Section 1042 deferral | Not treated as unrelated business income | Pass the Section 409(p) anti-abuse tests |
| S corporation, sales after 2027 | Deferral on up to 10 percent of the amount realized | Not treated as unrelated business income | Pass the Section 409(p) anti-abuse tests |
The S corporation income rule appears in Section 512(e)(3), which exempts ESOP-held employer securities from the unrelated business income rule. Our article on the ESOP exit strategy compares the sale with other exit routes.
What Does the Repurchase Obligation Mean for Cash Flow?
The repurchase obligation is the company's duty to buy back shares from employees who leave, retire or die, because shares of a private company have no public market. Federal law gives departing participants a put option, so a feasibility study must forecast those buybacks alongside loan payments to show the cash really exists.
Under Section 409(h), a participant can require the employer to repurchase shares under a fair valuation formula. The put option must stay open for at least 60 days after distribution, with a second 60-day window in the following plan year.
A useful study goes past the Section 409(h) minimum. It maps employee ages and tenure, estimates when large accounts will pay out, and tests whether the company can fund those payments while it still carries acquisition debt. Repurchase costs grow as the share value rises, so success can raise the bill.
Why Is the Feasibility Value Only a Range?
The feasibility value is only a range because the ESOP trustee, not the seller or the study, decides what price the plan pays. ERISA requires the plan to pay no more than adequate consideration, so the trustee must reach its own fair market value conclusion. The study gives the owner a realistic expectation, not a promise.
ERISA defines adequate consideration for private company stock as fair market value determined in good faith by the trustee or named fiduciary. The trustee's price can land below the owner's hopes, and the deal can still close.
Owners who understand the adequate consideration standard set better expectations. A sound study shows how the value range was built, which assumptions drive it and how sensitive it is to growth, margins and debt terms. Our guide to ESOP valuation requirements explains the standards in more depth.
Considering a Sale to Your Employees? Start With a Value Range Built for Your Structure.
What Are the Steps in an ESOP Feasibility Study?
An ESOP feasibility study follows a set order: confirm the owner's goals, build a preliminary value range, test debt capacity and payroll limits, compare tax structures, model repurchase costs and report a go or no-go result. Most steps rely on the company's historical financials and a credible multi-year forecast.
The first three steps set the base:
- Set the owner's goals for price, timing, control and legacy.
- Gather three to five years of financials and a forecast.
- Build a preliminary fair market value range.
The next four steps test the deal:
- Test bank debt, seller notes and the payroll limit.
- Compare C and S corporation structures and the seller's after-tax result.
- Model repurchase costs and the effect on current benefit plans.
- Report a recommendation and a structure to propose to a trustee.
A clear go result leads to hiring ESOP counsel and an independent trustee. A no-go result is still useful, because it shows what must change first.
How Virtue Advisors Supports ESOP Feasibility Work
Virtue Advisors provides ESOP Valuation Services for establishing or terminating an ESOP and for annual ERISA and DOL compliance. Virtue Advisors specializes in the valuation component of an ESOP and works with the client's legal, financial and tax advisors on implementation.
Virtue Advisors states that its valuation assignments are executed and reviewed by CVA and AICPA-qualified experts, with 100+ valuation reports delivered across 15+ industries. The firm offers flexible and customized solutions matching unique reporting needs, so a value range fits the structure the owner is testing.
Conclusion
An ESOP feasibility study answers three money questions before legal fees begin: can payroll carry the debt, which tax structure fits, and can cash flow fund future buybacks. Owners who get clear answers to those questions make better decisions, whether the result is go or no-go.
Start with honest numbers and a realistic value range. The study is only as good as the forecast and assumptions behind it.
Need a Value Range for Your ESOP Study? Talk to Virtue Advisors' CVA and AICPA-Qualified Valuation Experts.
Frequently Asked Questions
Jeet Chaudhary
Jeet Chaudhary serves as the Chief Operating Officer at Virtue Advisors, where he leads the firm’s Global Control Centre and oversees end-to-end operational excellence.